

At Hispanos Emprendedores, we explain how to apply for PPP loan forgiveness . The Paycheck Protection Program (PPP) served as a lifeline for U.S. businesses that suffered the consequences of the pandemic. The idea was to help them retain their employees. Below, we explain the requirements to obtain debt forgiveness.
How PPP works
The Paycheck Protection Program (PPP) was one of the economic relief options included in the CARES Act . It was created in March 2020 and its objective was to allow businesses to keep their employees on the payroll, as well as cover other expenses specified in the guidelines.
The federal government allocated 2 million dollars for this program, which closed on August 8 of this year. In that period it underwent several modifications to expand the participation of more companies. In total, 5.2 million loans worth more than $ 525,000 billion were made through the PPP, according to the SBA.
Accessing the program was very simple; no personal guarantees were needed. The interest rate was 1%, among other advantages, which made it popular with business owners. But the most attractive benefit was the possibility of requesting loan forgiveness under the PPP program.
After the disbursement of the funds, which in some cases took 8 weeks and in others 24, borrowers can request loan forgiveness.
For those companies that obtained loans of less than 50 thousand dollars, a simplified application was established that requires presenting less documentation and making fewer calculations.
Who is eligible for PPP loan forgiveness?
During this process doubts have arisen among the borrowers; for example, if the condemnation of the loans is automatic. It is not, in fact, the SBA made the requirements clear from the start.
To receive the conviction, the company must have supported the workers and used the funds for payroll. The resources could also be used for other eligible payments such as utilities, rent, and mortgage taxes.
The PPP loan forgiveness rules also state that 60% of the funds must be used for payroll payments.
In addition, they must maintain the payroll and pay the wages they had before the pandemic. Indeed, there are cases in which this is not possible, but they must have a way to show that they tried.
After reviewing the use of the funds, the SBA may condemn the entire loan or a portion of it.
How to apply for PPP loan forgiveness
The steps to request forgiveness are summarized as follows:
- Contact the lender and fill out the corresponding forms.
- Gather payroll and non-payroll documentation.
- Submit the application to the lender.
- Be attentive to any communication from the lender, who will receive the SBA's decision.
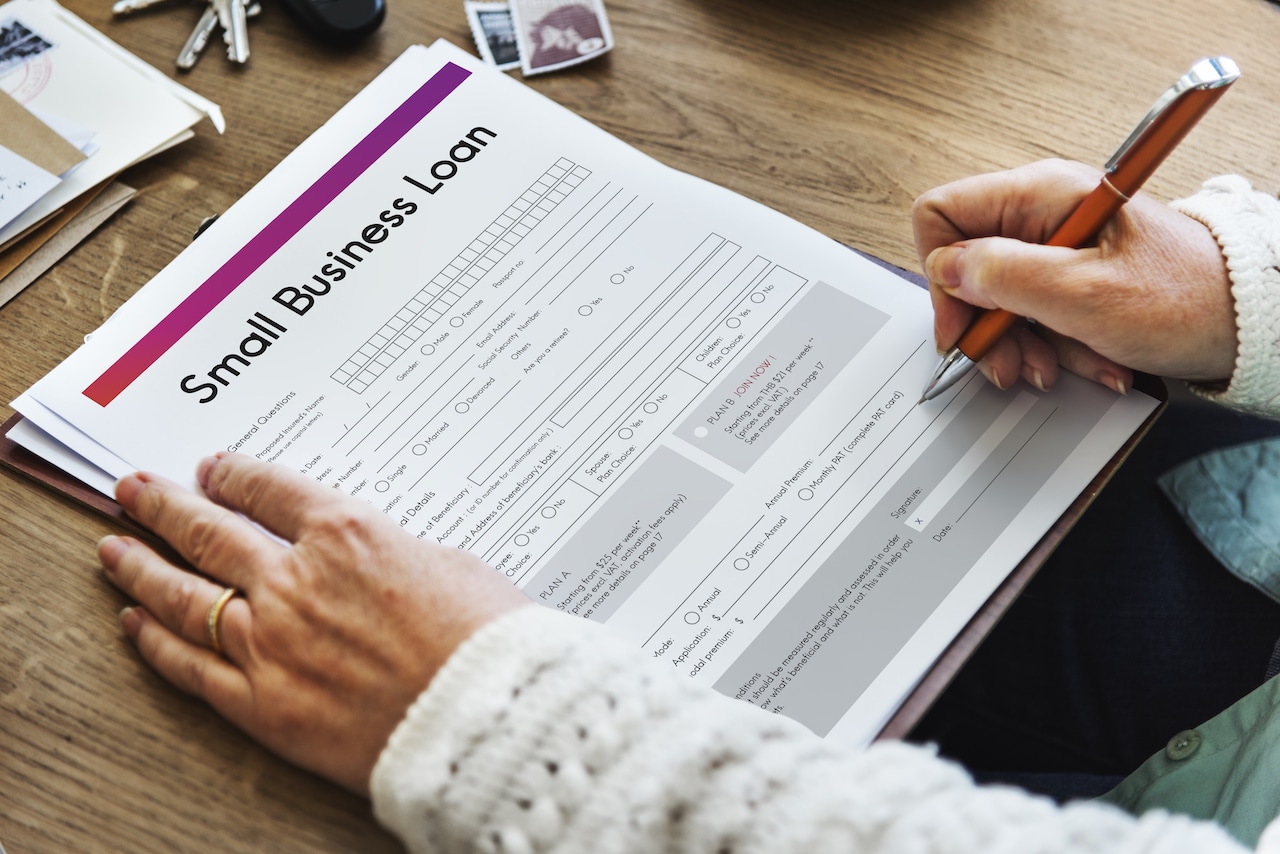
The lender is responsible for providing you with the appropriate PPP payment forgiveness form . The SBA forms are 3508, 3508EZ, or 3508S; the latter two are simplified versions. However, the lender may also provide you with an equivalent form.
As for the documents, these include bank account statements that report payroll payments; receipts or others that provide proof of contributions to the health insurance or retirement plan; tax forms.
Likewise, copies of invoices and receipts for services, payment of rent and mortgage interest must be delivered; among others.
After submitting the application, the SBA may evaluate the loan and communicate the amount awarded to you through the lender.
Application deadline for PPP loan forgiveness
There is a deadline for applying for PPP loan forgiveness . Borrowers can apply at any time before the loan matures. However, if they apply within 10 months of the loan's end, they are not required to make any payments.
That is, from the moment you apply (within those 10 months), until the SBA reports the amount sentenced, you will not pay anything. So if the loan is condemned in full, you will not make any payments. But if only part of it is convicted or the application is denied, then you will have to pay what is due before expiration.
SBA clarifies doubts
If you are a beneficiary of the Payment Protection Program and you still have questions about the condemnation of the loans, review the SBA documentation.
The agency, together with the Treasury Department, prepared a document answering frequently asked questions about PPP loan forgiveness. There you will find information about the salary and non-salary costs that are included, reductions, what happens when an economic injury disaster loan was received, etc.
Consult with your lender so that it is clear to you how to request the condemnation of PPP loans.
Read the Hispanic Entrepreneurs magazine